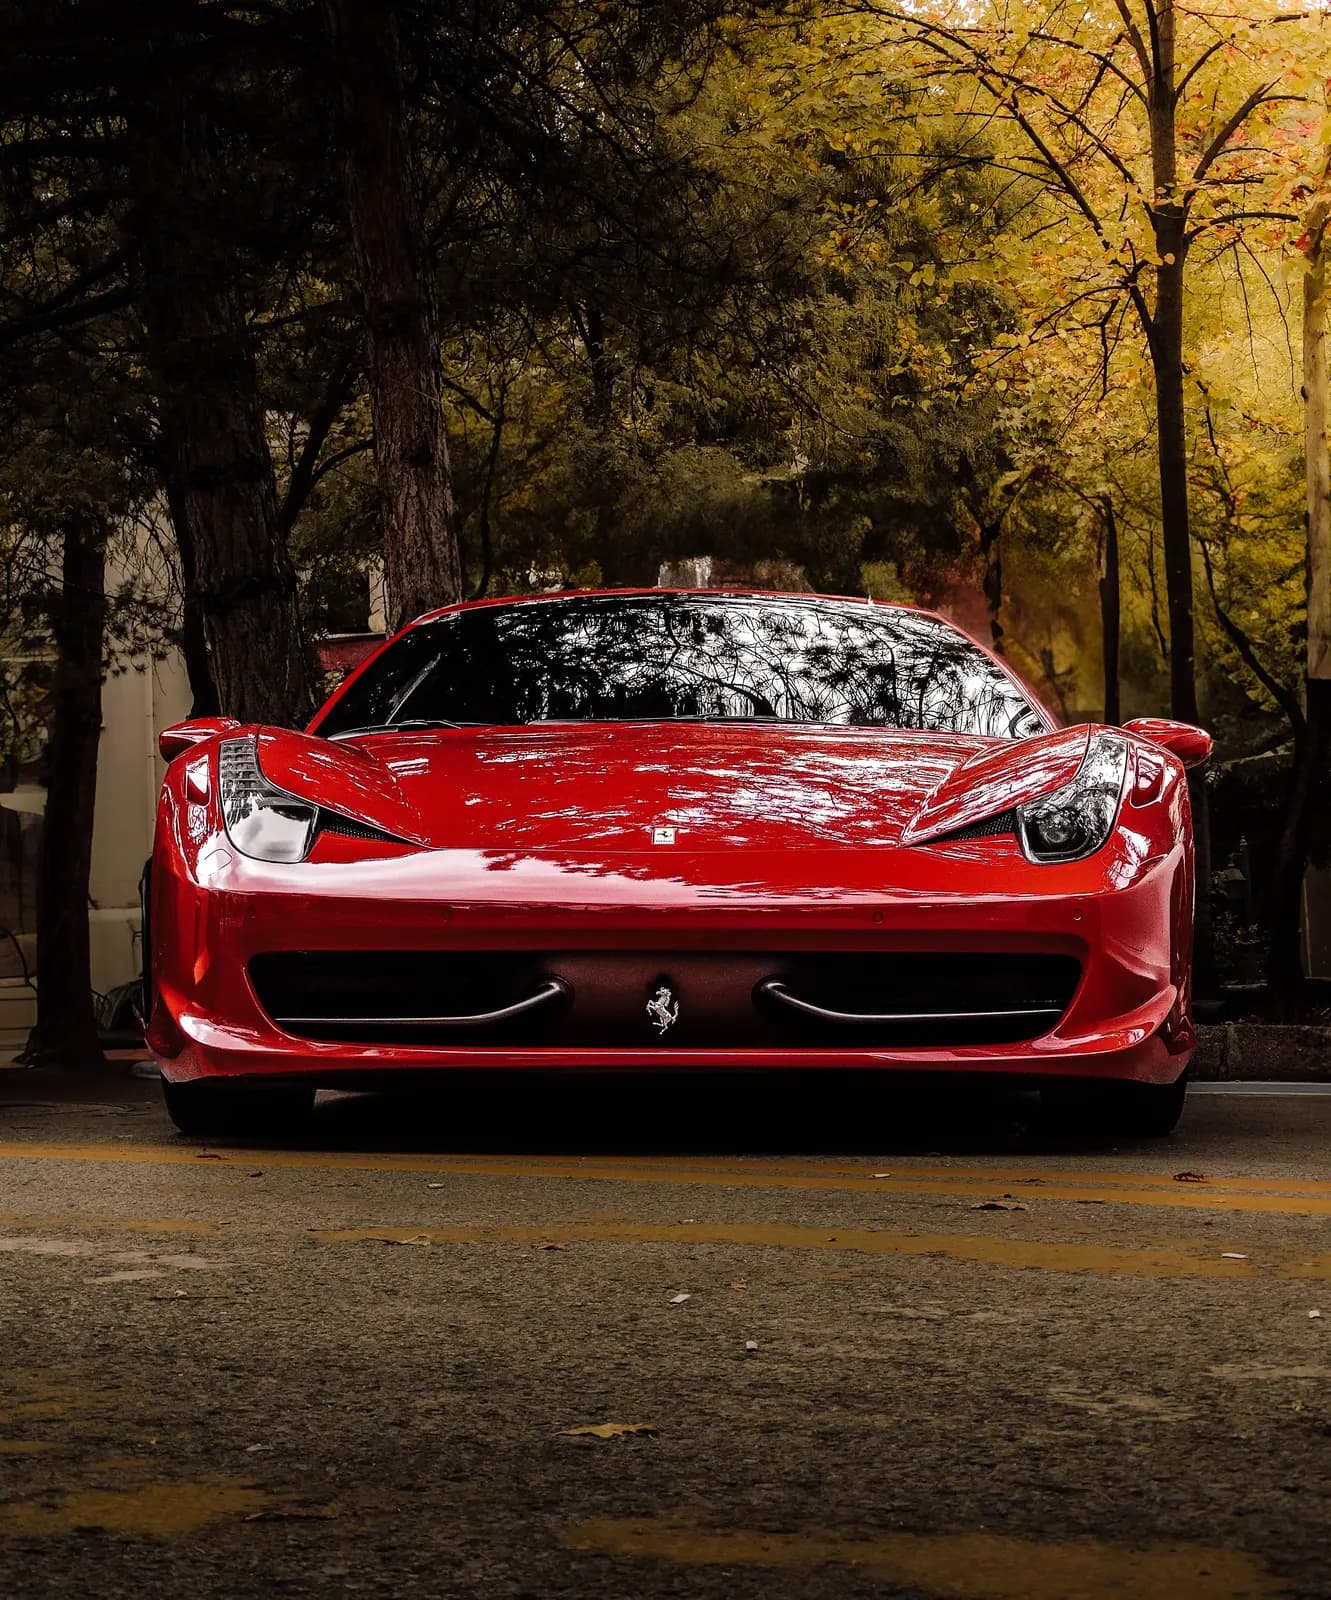
Ferrari financing
Modern, classic and halo Ferrari, financed against the car and its documentation. Amounts to $5,000,000. Subject to credit approval.
Up to $5,000,000 · Terms up to 180 months · Dealer, private seller or auction
What financing a Ferrari is actually like
Ferrari is the marque where documentation most clearly separates two otherwise identical cars. Provenance, factory records and certification carry real weight in the valuation, and their absence is just as visible.
It is also where the top of the market has been most active. Ferrari set a run of record prices through early 2026, including across its halo models — which makes recent comparables, rather than last year's figures, the basis for any sensible appraisal.
What an appraiser looks at on a Ferrari
The things that move the number on this marque specifically — and that a general-purpose valuation keyed to year, make and model cannot see.
Factory certification is a valuation input, not a formality
Ferrari Classiche certifies the authenticity and originality of older cars, confirming that major components are as the factory built them. A certified car and an uncertified one of the same model are not the same asset, and the gap between them can be substantial.
Halo models are appraised against a moving market
The 288 GTO, F40, F50, Enzo and LaFerrari trade in a narrow, well-documented market that moved sharply through 2026. On a car bought near the top of a run, expect loan-to-value to be calculated against current comparables rather than the price paid.
Service history is unusually consequential
Major scheduled work on a Ferrari is expensive and well defined, and whether it has been done — and by whom — is reflected directly in value. On older mid-engined cars in particular, a documented engine-out service is a material part of the file.
Specification narrows the buyer pool
Colour combination, interior trim and options affect resale more sharply than on most marques. A car in a sought-after original combination appraises differently from the same model in an unpopular one, which bears on loan-to-value as much as it does on resale.
What we finance
Model years 1920 to current. Eligibility turns on appraisal and condition rather than age, which is the practical difference between this and a conventional auto loan.
What strengthens a Ferrari file
Documentation is not administrative here — it is part of the valuation. Gather it before you negotiate, not after.
- Classiche certification where it exists, or a clear account of why it does not
- Complete service history, including major scheduled work and who carried it out
- Original specification documentation confirming colour, trim and options as built
- Ownership chain, which on collectible Ferrari is part of the value rather than just the paperwork
Financing is arranged through independent participating sources and is subject to credit approval, vehicle eligibility and appraisal. Not all vehicles, amounts or terms will qualify.
Model it before you commit
Move the down payment and the term, and read the total rather than the monthly. Output is illustrative only and is not an offer of credit.
Illustrative example only
$3,217/moapproximately
- Vehicle price
- $250,000
- Down payment
- $50,000
- Amount financed
- $200,000
84 monthly payments at 8.99% APR
Estimated Payment Only. This calculator is provided for illustrative purposes only and does not constitute a credit application, approval, offer, commitment to lend, or guarantee of financing. The interest rate used is an estimate and may not reflect the rate for which you qualify. Actual loan terms, rates, monthly payments, and approval are subject to creditworthiness, vehicle eligibility, lender requirements, and other underwriting factors. Estimated payments do not include taxes, title, registration, insurance, or other applicable fees. Digital AutoFi does not offer or set the displayed terms. Please refer to our disclosures for additional information.
Ferrari financing, answered
Before you apply
Looking more broadly? Exotic car financing covers the program across every marque we finance.
Ready to finance your Ferrari?
Tell us the car, the specification and where you found it. A specialist reviews it and tells you what is realistic before you commit to anything.
- Initial feedback in about an hour during business hours
- No fee to submit an application to Digital AutoFi. Other transaction or third-party fees may apply.
- Programs available in all 50 states